

Photo Pieter Beens
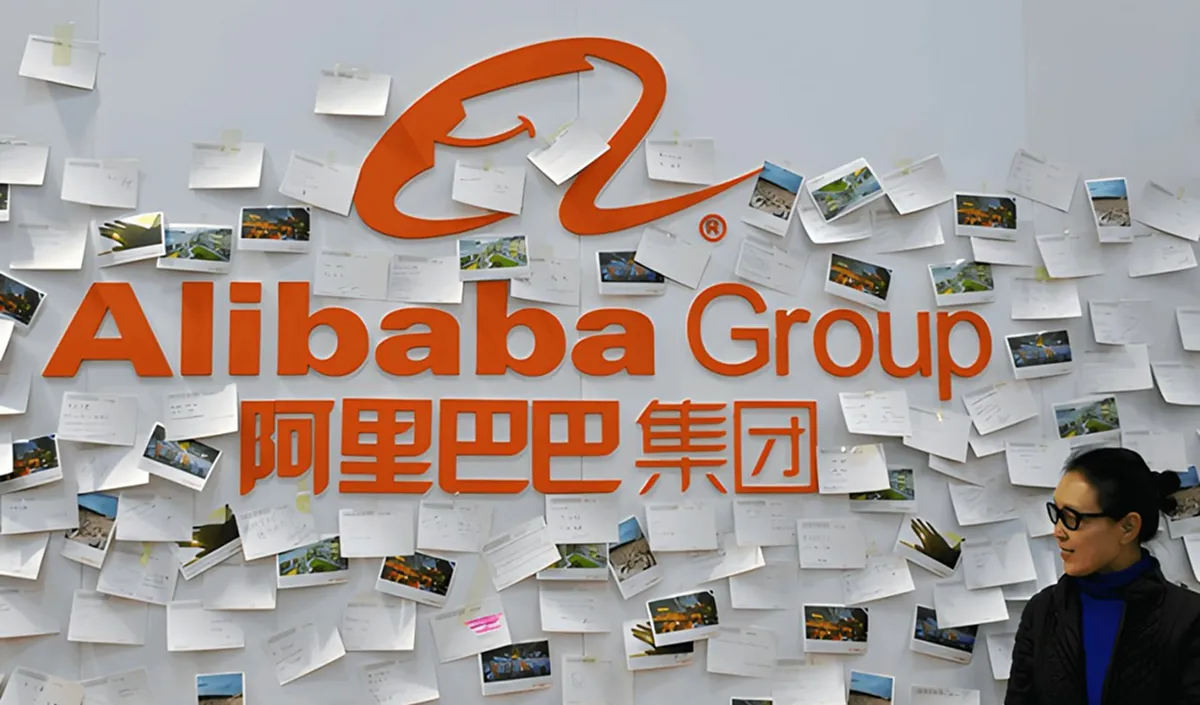
For the quarter ending 30 September, the Hangzhou-based tech giant’s revenue exceeded the figure from a year ago by 10 per cent, reports Boursorama. Meanwhile, net profit attributable to the company’s shareholders surged by 207 per cent, reaching 64.5 billion yuan ($9.6 billion).
This sharp rise in profit is largely attributable to an increase in investment income and therefore cannot be directly linked to an improvement in operating results. By way of comparison, in the previous quarter (April–June), Alibaba’s net profit fell by 76 per cent year-on-year to 10.5 billion yuan.
Cloud business emerges as the main beneficiary of AI
Alibaba Group CEO Eddie Wu attributed the positive trend to rising revenue from artificial intelligence products. According to him, the company gained additional momentum thanks to the development of its own chips, computing infrastructure and technologies for creating AI models and intelligent agents.
The cloud business has seen a particularly marked acceleration. Alibaba Cloud’s revenue from external customers rose by 67 per cent year-on-year. This has underpinned the overall growth of the cloud division and contributed to an increase in its profitability.
Alibaba is actively ramping up investment in artificial intelligence, with the aim of turning its technological developments into a sustainable source of revenue. In September, the company announced plans to expand its international network of data centres, with a particular focus on Europe and the Middle East.
In addition, Alibaba unveiled its new AI chip, the Zhenwu V900. According to the company, its performance is three times higher than that of the previous model, the Zhenwu M890.
For investors, the key question remains whether Alibaba will be able to recoup its large-scale investments in AI and turn its technological achievements into a sustainable source of revenue.
Follow our updates
Have information for the newsroom? Share it with Logos-Press


Comments
0No comments yet. You can start the conversation.
Comments are open to readers with a Logos Press account.
Sign in to comment