

The subtext of Marcus’s message was clear: it was time for central banks to let Facebook manage the global payments system. There was a new kid on the block, with very deep pockets, and the old guard had better step aside.
The message was not well received. One could watch the hackles of the financial titans rise to the ceiling and beyond. Soon after, regulators around the world launched a coordinated effort to throw sand in Libra’s gears. Facebook tried to salvage the project, rebranding it as Diem. But the financial gods are not to be mocked, and the new kid was hounded out of town. Libra/Diem’s intellectual property was eventually sold to a small California bank, which subsequently shut down.
But Libra left its mark. Privately, some central bankers were impressed by the technology, and Marcus’s observation that international payments systems can be too slow, expensive, and cumbersome was hard to dismiss. Libra jolted many central banks into action, prompting them to work on digital currencies of their own, and the Bank for International Settlements began tracking these projects. With cash use declining sharply, it seemed like a matter of time before the major central banks began issuing digital money.
The central banks’ wait-and-see approach
At first glance, things seem to be moving in that direction. The latest edition of the Atlantic Council’s central bank digital currencies (CBDCs) tracker shows that 146 countries are exploring the idea. So, can we expect a wave of CBDCs crashing over the financial system in the next few years?
Maybe, or maybe not. So far, only three countries—the Bahamas, Nigeria, and Jamaica—have moved from planning to launch, and their experience to date has been underwhelming. Circulation of the Bahamian SandDollar has stagnated over the past three years, while the Nigerian eNaira remains a niche product. China’s e-CNY, meanwhile, is still in its pilot stage. Local demand has not taken off as hoped.
Several advanced economies have also decided not to move ahead, even though the preparatory work had already been done. In the United States, the Federal Reserve did some insightful work on CBDCs—codenamed Project Hamilton for added gravitas—before concluding the study in 2023. In July, Congress passed the 21st Century ROAD to Housing Act, which prohibits a dollar CBDC until 2031.
An executive order by US President Donald Trump last year left no doubt about his administration’s opposition to a digital dollar. And with Fed Chair Kevin Warsh also calling it “a bad policy choice,” we can expect no US movement on a CBDC for the foreseeable future.
Other central banks have also had second thoughts. The Bank of Canada—still, for now, managing a separate dollar—has put its CBDC work on the back burner. In September, a paper by the Reserve Bank of Australia concluded that the country’s retail payment system was serving households and businesses well, and that there was no clear case that a retail CBDC would serve the public interest.
Norway’s Norges Bank has gone further than others in explaining its decision not to proceed. It has concluded that a retail CBDC is not the most effective way to promote innovation, strengthen resilience, or improve payment efficiency. It is, however, continuing to work on tokenization and the use of central-bank money in settlement systems.
The ECB’s resolute stance
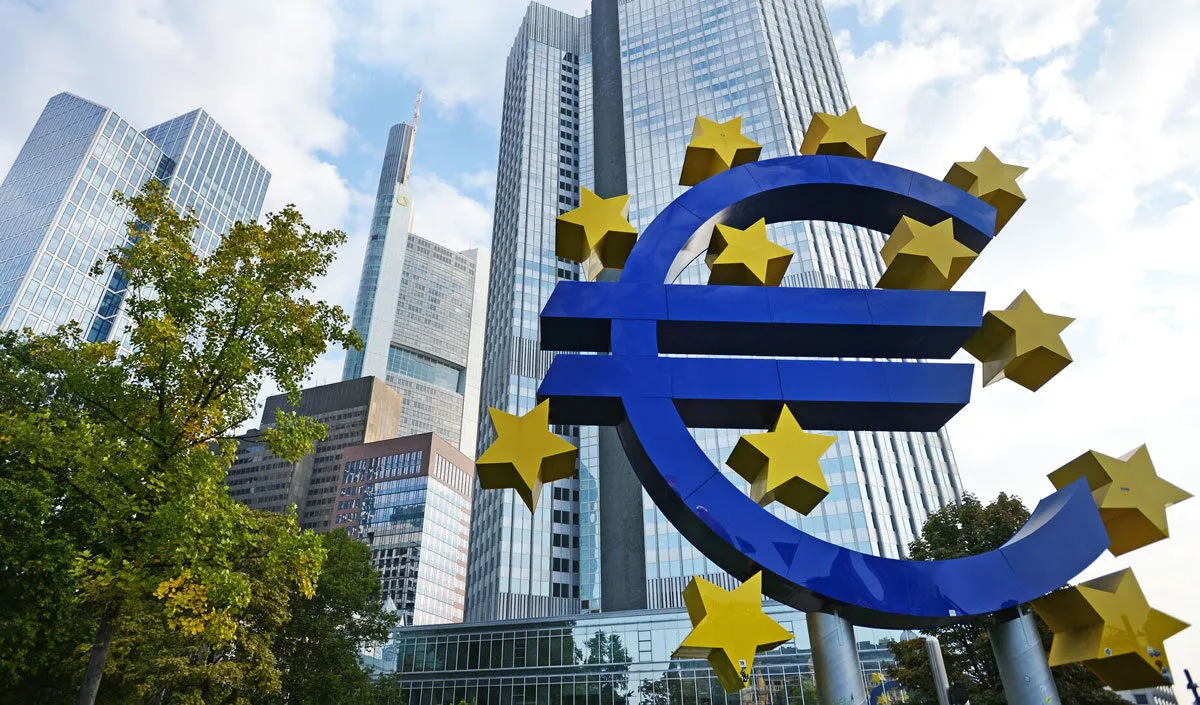
But in Frankfurt, the mood is different. The European Central Bank remains as committed as ever to its digital euro and has recently secured the backing of the European Commission. It plans to be ready to issue its digital currency in 2029, provided the necessary legislation is passed in time.
Europe’s commercial banks have argued strenuously against the project, not least because of its cost. They claim implementation will cost €18 billion ($20 billion), compared with the ECB’s estimate of €4–6 billion. But the ECB has so far won the political argument, and its president, Christine Lagarde, has made issuance a personal crusade.
Why this European exceptionalism? The ECB argues that a digital euro will create a fully integrated retail payment system, which the EU currently lacks. Europe, in its view, is too reliant on US-owned payment networks, with the additional threat of dollar-denominated stablecoins.
There are echoes here of the debate over European defense. Can Europe continue to rely on American benevolence after its experience with Trump? The risks of that dependence became clear in October, when the Trump administration sanctioned International Criminal Court officials and judges, cutting them off from the US financial system.
Digital currencies thus join the growing list of policy areas on which the US and Europe diverge. Compared with their differences over Ukraine and Trump’s tariffs, this may seem like a minor issue. But if digital currencies eventually become necessary, the ECB could gain a first-mover advantage in setting the legal, technical, and compliance standards for CBDC infrastructure. US companies operating in Europe may then find themselves at a disadvantage. And if cross-border euro-denominated payments become relatively cheaper, using the euro will be more attractive.
On the other hand, if the ECB throws a party and no one shows up—if usage of the digital euro remains modest—Europe will be left with a costly dud. It’s a gamble, which is no doubt why the Bank of England is sitting on its hands for the moment, waiting to see how the croissant crumbles.
Howard Davies,
a former deputy governor of the Bank of England, is a professor at Sciences Po.
© Project Syndicate, 2026.
www.project-syndicate.org
Follow our updates
Have information for the newsroom? Share it with Logos-Press





Comments
0No comments yet. You can start the conversation.
Comments are open to readers with a Logos Press account.
Sign in to comment