
Ana Groza
Targeted and specific consultations
The consultation process itself has changed slightly. Whilst in previous years it was broader in scope, involving all stakeholders and featuring professional discussions on the concept and key proposed changes, this year’s consultations were more targeted and specific. The Ministry of Finance has mainly focused on sector-specific changes and has organised more than a dozen meetings with associations and representatives of specific business sectors.
This is due to the rushed drafting of the second draft of the 2027 tax policy and the short timeframe allowed for discussion, as well as the Ministry’s challenging task of meeting these deadlines and drawing up the budget for the following year once the policy has been approved.
At the same time, some tax experts reacted to this with bewilderment and regret, as they felt there had not been sufficient public and professional debate. This could have a negative impact on the quality of tax policy.
Many proposals and opinions were put forward during the consultations, and Logos Press has previously outlined the main ones. Many of these were also reflected in the conclusions on the draft Tax Policy 2027, prepared by the National Confederation of Employers of Moldova (CNPM).
Clear application of the rules
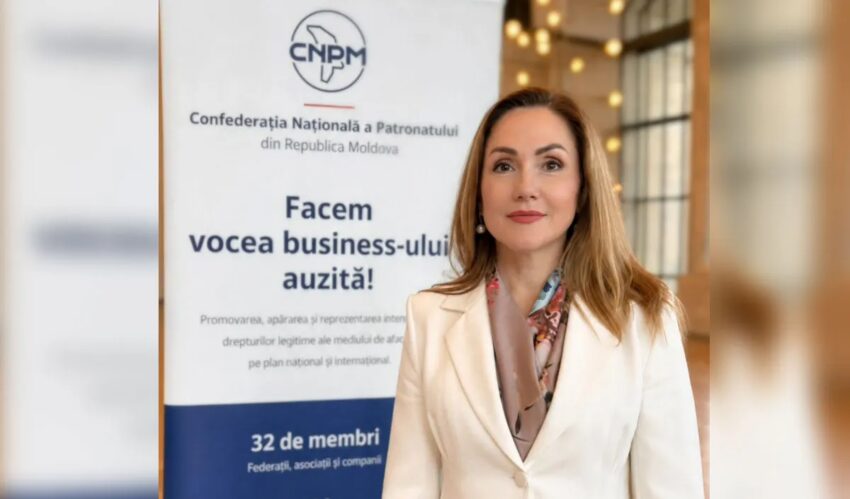
First and foremost, its members identified the predictability of tax policy as one of the key priorities for doing business. “For an entrepreneur, it is not only the amount of tax that matters, but also the certainty that the rules will be clear and applied consistently tomorrow just as they are today,” says Ana Groza, President of the CNPM.
At the same time, the tax burden must take into account the economy of a specific sector, bearing in mind its particular characteristics and current situation. “That is why we are raising the issue of an 18 per cent rate on the income of enterprises providing financial services,” she continues. “Banks, insurance companies and currency exchange bureaux cannot automatically be lumped together simply because they fall within the same group under the Classification of Economic Activities (CAEM).”
As CNPM members point out, in the insurance sector, for example, the additional revenue for the state budget by 2025 would amount to only around 5 million lei. However, it must be borne in mind that this sector faces significant capitalisation costs due to the transition to European requirements.
In this context, Logos Press published the views of Marina Solovieva, Programme Director at Expert Grup, who described the increase in the corporation tax rate for the financial sector from 12 per cent to 18 per cent as an “unwelcome ‘gift’” for the recently opened International Stock Exchange of Moldova (BIMx). She noted that, having barely begun operations, the exchange would be subject to higher taxation, which is unlikely to have a positive impact on the development of the stock market in Moldova.
Equal relations between the state and the taxpayer
Business leaders also insist that businesses’ working capital should not become a free source of funding for the state. Hence their proposal for accelerated VAT refunds: within 15 working days for companies with low tax risk.
Overall, employers believe that the relationship between the state and the taxpayer should be more symmetrical. If a business pays a penalty for a delay, then a similar principle should apply where the state unreasonably delays the refund. The same applies to limitation periods and the set-off of liabilities.
At the same time, they emphasise that a distinction must be made between an error and a deliberate breach. They therefore propose introducing a mandatory ‘first formal breach without penalty’ principle. In other words, the business should first be given the opportunity to rectify the error, with a fine being imposed only if the error is not rectified or in the event of a repeat offence.
Clearly, this does not apply to cases of fraud or tax evasion.
Stimulating investment and employment
Another important point raised by employers is that tax policy should stimulate investment and employment. They are therefore proposing a more appropriate approach to employers’ expenditure on staff meals, transport and accommodation, particularly in the context of a labour shortage.
Furthermore, the association’s members are once again raising the issue of abolishing the ‘construction’ levy, amounting to 0.5 per cent of the investment value, which investors currently pay. This is all the more relevant given that a provision has recently been introduced into legislation obliging investors to pay this levy on every project.
“We also have proposals specific to our sector – VAT along the agri-food supply chain, excise duties, the energy sector, transfer pricing and so on,” says Ana Groza. “But if we were to summarise our position in a single point, it is that we are not opposed to the state’s fiscal objectives. We are in favour of these being achieved through clear rules, voluntary compliance and the expansion of economic activity, rather than by placing an additional burden on conscientious businesses.”
This story was translated with the assistance of artificial intelligence.The translation was also reviewed by the Logos Press editorial team.
Follow our updates
Have information for the newsroom? Share it with Logos-Press

Comments
0No comments yet. You can start the conversation.
Comments are open to readers with a Logos Press account.
Sign in to comment