

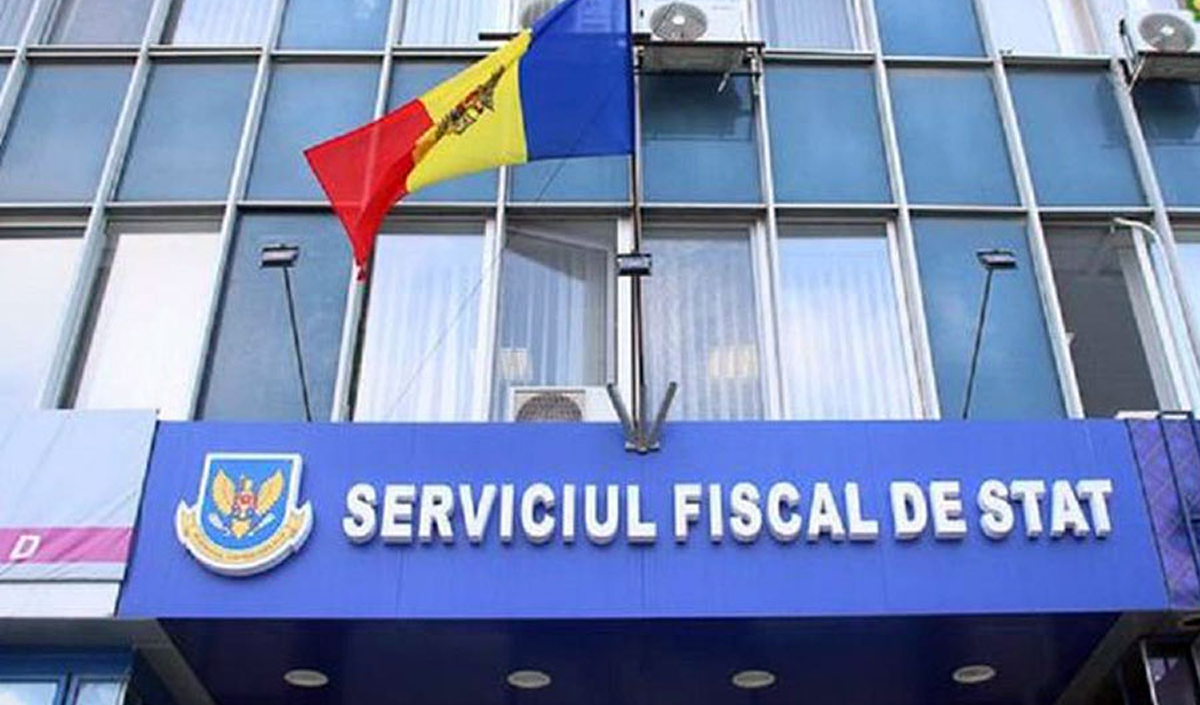
Communication between the State Tax Service and those required to submit reports online will take place via the taxpayer’s personal online account on the tax service’s website or the government portal for legal entities.
Administrative documents, summonses, other official notices, and responses to enquiries will be communicated to them in the same way. In this context, the State Tax Service will amend the regulations governing the procedure for communicating its official notices, bringing them into line with the new provisions of tax legislation.
Furthermore, the amendments made to the Civil Code provide that communication between public authorities and persons carrying out business activities will take place via the government portal for legal entities. In both cases, documents will be deemed to have been received on the next working day following their transmission.
It is also proposed to establish new rules for the service of administrative acts on individuals. Communication with them will take place via the electronic means specified by them, including through a representative.
The requirement to display public notices on the notice board at the State Tax Service’s central office will also be abolished. However, the obligation to display such notices at the State Tax Service’s regional offices will remain in place.
Comments on the draft may be submitted until 20 October 2026.
This story was translated with the assistance of artificial intelligence.The translation was also reviewed by the Logos Press editorial team.
Follow our updates
Have information for the newsroom? Share it with Logos-Press
Comments
0No comments yet. You can start the conversation.
Comments are open to readers with a Logos Press account.
Sign in to comment